All Categories
Featured

Affordable Family Health Insurance for 2026
Among the most attractive features is the capability to access the cash value through policy loans and withdrawals, typically on a tax-free basis, provided the policy is structured properly and remains in force. Policy loans are generally not considered taxable earnings. Withdrawals approximately the quantity of premiums paid (your cost basis) are normally tax-free.
It's important to comprehend that if the policy lapses or is surrendered, impressive loans and gains may end up being taxable. The adjustable premium payments and prospective death benefit choices supply a degree of flexibility not always discovered in other irreversible life insurance coverage items. While concentrating on money development, the policy still provides a crucial death advantage for beneficiaries, using monetary protection for your enjoyed ones.
The "finest IUL policies for cash accumulation" will typically feature competitive caps, participation rates, and manageable internal costs. The "best company for IUL" for retirement preparation might likewise provide beneficial loan provisions.
Since today's cap is not the entire story, our comparison of IUL renewal cap rates: F&G vs Pacific Life and Lincoln takes a look at how caps have actually changed in time. While IUL offers compelling possible benefits, it's vital to approach it with a clear understanding of the associated risks and costs.
Cheap Family Medical Quotes
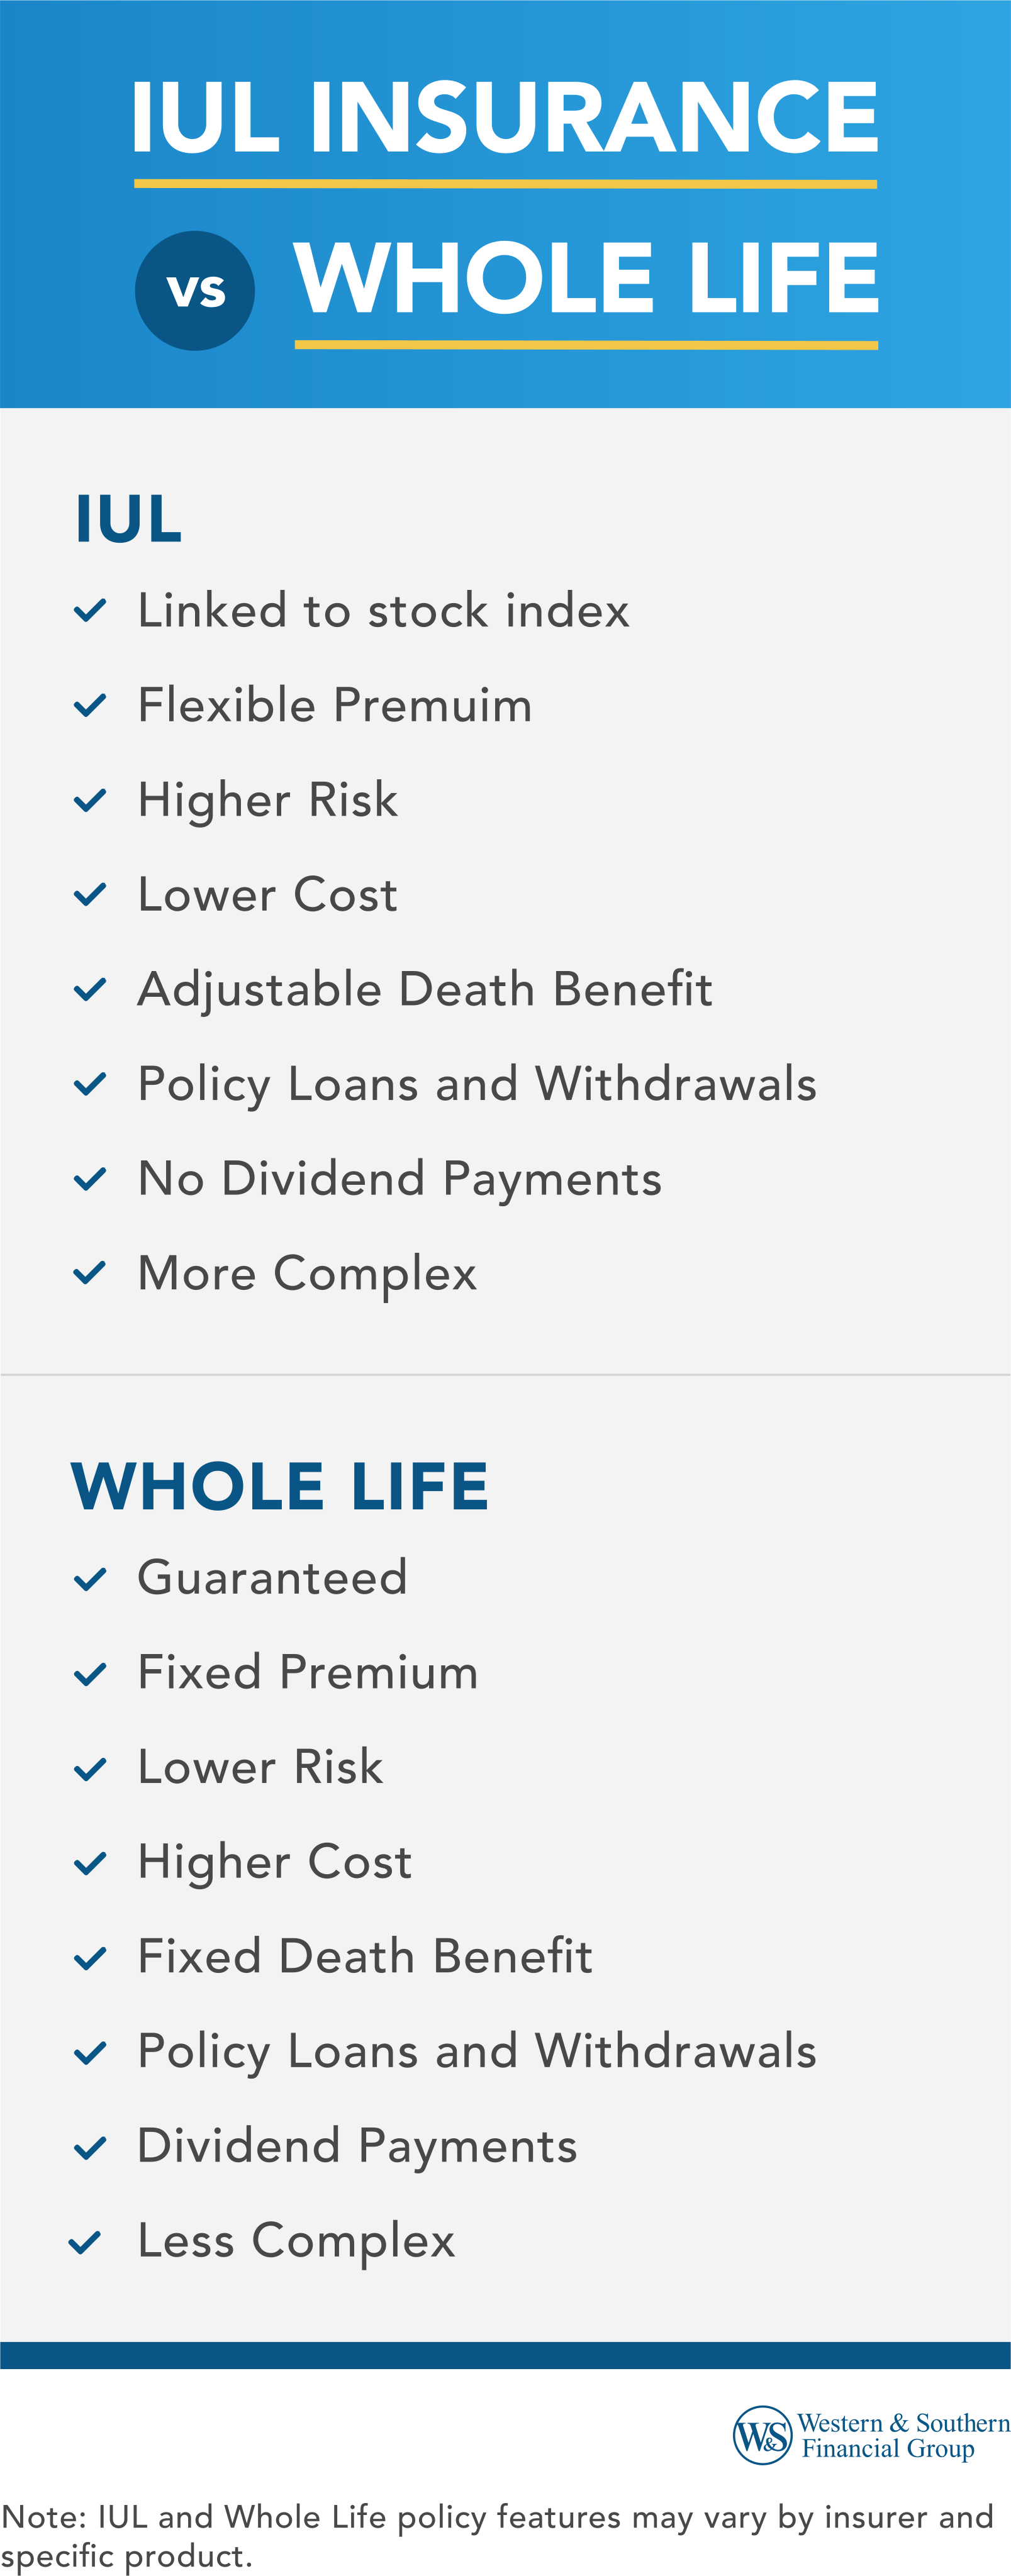
IUL policies are naturally more complicated than term life or even standard whole life. Policy illustrations, which project future cash worth growth, are based on numerous presumptions about index performance, crediting rates, policy expenses, and loan use.
Insurance in Beverly Hills CAIUL policies have various internal charges that reduce money value growth. These can consist of: The charge for the pure death benefit security.
Costs for any extra benefits contributed to the policy. Fees applied if you surrender the policy or withdraw significant amounts, typically within the very first 10-15 years. These costs are subtracted regardless of index performance. High internal costs can considerably hinder money value accumulation, particularly in years with low or zero interest crediting.
While the flooring secures against direct market * losses *, it doesn't ensure positive returns. If the connected index carries out inadequately or remains flat for extended periods, your money worth may just earn the flooring rate (typically 0%). After policy costs are subtracted, the money worth could potentially decrease in such years.
Even in growing market years, your credited interest won't go beyond the cap. Participation rates below 100% more lower the credited interest relative to the index gain. Providers can sometimes change non-guaranteed elements like caps and involvement rates over the life of the policy (within legal limits), which might impact long-lasting efficiency.

Latest Posts
Medicare Part D Coverage Tips for 2026
Top Indexed Universal Life Policies for Wealth Growth
Evaluating Term Life Insurance Rates